There is a financial concept that gets thrown around a lot and it has to do with the difference between how much of your income you pay to the government and what is your tax bracket. Many people believe that their tax bracket is the rate that determines how much of your annual pay is forfeited to the IRS.
Fortunately, that’s not how federal income taxes work.
The United States uses a progressive income tax system. As your taxable income increases, portions of that income are taxed at progressively higher rates. But moving into a higher tax bracket doesn’t mean all your income suddenly gets taxed at that higher rate.
To understand why, we need to distinguish between two concepts: your marginal tax rate and your effective tax rate.
What Is Your Marginal Tax Rate?
Your marginal tax rate is the rate applied to the last dollar of your taxable income. Generally, it’s also the rate you’ll pay on your next dollar of ordinary taxable income.
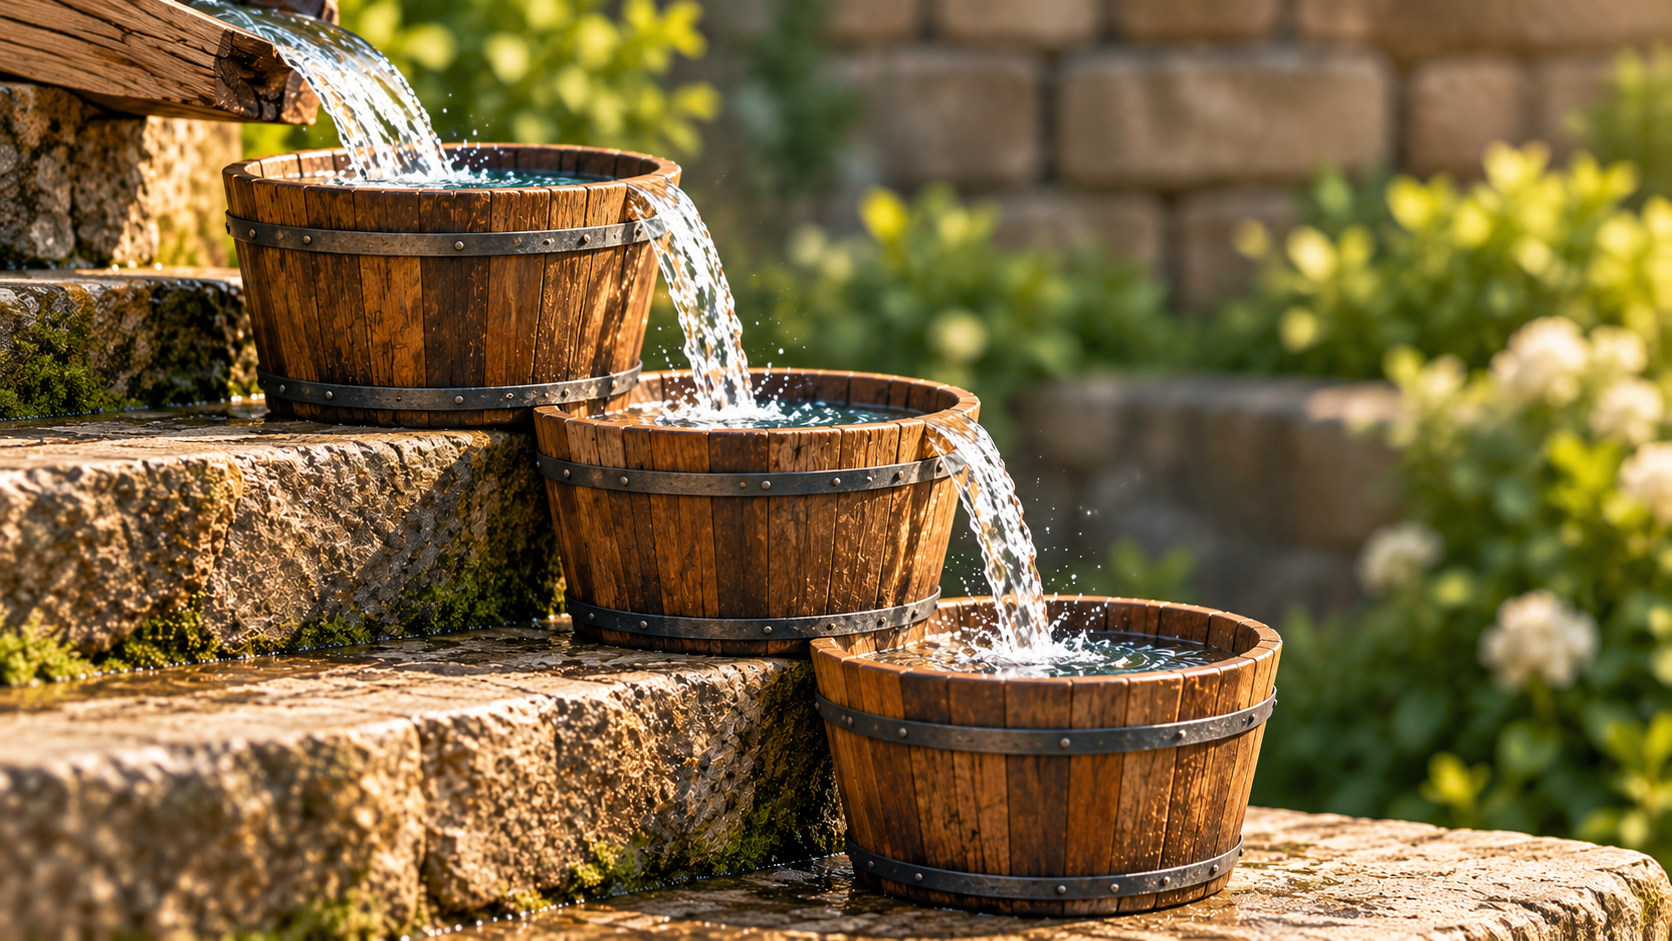
Think of it this way. Imagine your income accumulating throughout the year, filling up one tax bucket. Once the lowest bucket is filled, the income spills over and starts filling the next bucket.
For a married couple filing jointly in 2026, the standard deduction creates the first bucket, which holds the first $32,200 of income and charges a 0% federal income tax. The next $24,800 of taxable income spills over into the next bucket and is charged a 10% income tax. Once that bucket is filled, additional taxable income spills over into the 12% bucket.

But here’s the important part: earning enough to enter the 12% bracket doesn’t cause the income in the 10% bracket to be taxed at 12%. Those dollars remain subject to the lower rate.
For example, in 2026, married couples filing jointly pay:
- 10% on their first $24,800 of taxable income.
- 12% on taxable income from $24,801 up to $100,800.
- 22% on taxable income from $100,801 up to $211,400.
Higher income levels have additional brackets, but these three will be enough for our example.
As we showed above, moving into the 22% bracket doesn’t change the tax rate on the dollars already taxed at 10% or 12%. Only the income that falls into the new bracket gets taxed at 22%.
Meet Sam
Let’s return to Sam, who appeared in my earlier article about Roth 401(k) contributions.
Sam is married, files a joint tax return, and his household earns $100,000 annually.
For simplicity, we’ll assume that his household has no other income, takes the standard deduction, and doesn’t qualify for additional deductions or tax credits. In 2026, the standard deduction for married couples filing jointly is $32,200.
That means Sam’s household has:
- Gross income: $100,000
- Standard deduction: $32,200
- Taxable income: $67,800
Notice that Sam doesn’t pay federal income tax on the full $100,000. His taxable income is only $67,800.
Now let’s calculate his federal income tax.
Remember our tax table from above?
| Income Range | Federal Tax Rate |
|---|---|
| $0-$24,800 | 10% |
| $24,801-$100,800 | 12% |
| $100,801-$211,400 | 22% |
The first 24,800 dollars are taxed at 10%, producing $2,480 in taxes.
The remaining 43,000 dollars (67,800 taxable income – 24,800 already taxed at 10%) are taxed at 12%, producing another $5,160. Note that since all of Sam’s taxable income fits into the first two brackets, none of Sam’s income is taxed at the 22% rate.
Add those amounts together, and Sam’s total federal income tax is $7,640.
Because his last dollar of taxable income falls into the 12% bracket, Sam’s marginal tax rate is 12%.
But that doesn’t mean he paid 12% of his entire income in federal income taxes.
What Is Your Effective Tax Rate?
Your effective tax rate measures the percentage of your income that you actually pay in taxes.
For our purposes, we’re calculating federal income tax as a percentage of gross household income.
The formula is straightforward:
Effective tax rate = Total federal income tax ÷ Gross income
Let’s return to Sam. Remember, he made $100,000 for the year and paid a total of $7,640 in Federal income taxes. Therefore, we can calculate Sam’s effective tax rate as follows:
$7,640 ÷ $100,000 = 7.64%
So Sam has two different tax rates:
- Marginal tax rate: 12%
- Effective federal income tax rate: 7.64%
Both are correct. They simply answer different questions.
His marginal rate tells us how his next dollar of ordinary taxable income will generally be taxed. While his effective rate tells us what percentage of his total household income goes toward federal income taxes.
Why Does the Difference Matter?
Imagine Sam receives a $10,000 raise.
His household income increases to $110,000. Assuming nothing else changes, his taxable income rises to $77,800.
He’s still in the 12% marginal bracket, so the additional $10,000 produces $1,200 in federal income taxes.
Sam keeps $8,800 of his raise before considering payroll and state taxes.
His total federal income tax increases to $8,840, and his effective rate rises slightly to approximately 8.04%.
A higher tax bracket doesn’t retroactively increase the tax rate on the income you’ve already earned.
This distinction also matters when making financial decisions.
For example, contributions to a traditional 401(k) generally reduce your current taxable income. The contributions typically reduce your last dollar of earnings. Therefore the immediate federal income tax savings are determined by your marginal tax rates, not your effective tax rate.
Returning to Sam. Suppose he decides to contribute $10,000 of his $100,000 earnings to a traditional 401(k). That would reduce his taxable income from $67,800 to $57,800.
The first 24,800 dollars are still taxed at 10% and still produce $2,480 in taxes. But now he only has 33,000 dollars of taxable income taxed at 12%, producing only $3,960 in taxes.
His new total tax amount is $6,440 vs the original $7,640, a savings of $1,200 or 12% of the $10,000 saved in his 401(k).
Similarly, understanding marginal rates is important when considering additional taxable income, such as interest, bonuses, or Roth conversions.
Your effective rate is useful for understanding your overall federal income tax burden. Your marginal rate is generally more useful when evaluating the tax consequences of earning, saving, or converting additional dollars.
The Bottom Line
Your tax bracket doesn’t tell you what percentage of your income you actually pay in federal income taxes.
It tells you the rate applied to the highest portion of your taxable income.
Your effective tax rate tells you how much of your total income goes toward federal income taxes.
Your marginal tax rate helps you make financial decisions. Your effective tax rate helps you understand the results.


Leave a Reply